Savings account rate revisions in Singapore rarely bring good news, so this one is worth a closer look. With effect from 1 November 2026, UOB has raised the interest rates on the UOB Stash Account, lifting the maximum effective interest rate from 1.50% p.a. to 1.92% p.a. on a balance of S$100,000. That works out to up to S$1,920 in interest a year, up from roughly S$1,500 previously.
Photo Credit: UOB
The qualifying criteria are unchanged, which remains the main appeal of the Stash Account. There is no salary credit, no minimum card spend and no bill payment requirement. You simply need to maintain or increase your Monthly Average Balance (MAB) compared to the previous month. The base interest remains at 0.05% p.a. across all tiers. The changes are entirely in the bonus interest, with the biggest jump on the final S$30,000 tranche.
| Monthly Average Balance | Previous Total Interest | New Total Interest (from 1 Nov 2026) |
|---|---|---|
| First S$10,000 | 0.05% p.a. | 0.05% p.a. |
| Next S$30,000 | 1.40% p.a. | 1.50% p.a. |
| Next S$30,000 | 1.60% p.a. | 1.90% p.a. |
| Next S$30,000 | 2.00% p.a. | 3.00% p.a. |
| Above S$100,000 | 0.05% p.a. | 0.05% p.a. |
| Effective rate on S$100,000 | 1.50% p.a. | 1.92% p.a. |
The tiered structure means the headline 1.92% p.a. only applies if you park the full S$100,000. Here is how the annual interest works out at different balances, assuming you qualify for bonus interest every month:
S$40,000: about S$455 a year (effective 1.14% p.a.), up from S$425
S$70,000: about S$1,025 a year (effective 1.46% p.a.), up from S$905
S$100,000: about S$1,925 a year (effective 1.92% p.a.), up from S$1,505
The sweet spot is clearly the final tranche between S$70,000 and S$100,000. Every dollar in that band now earns 3.00% p.a., a full percentage point more than before. On a full S$100,000 balance, the revision puts roughly an extra S$420 a year in your pocket for doing absolutely nothing differently. Anything above S$100,000 drops back to 0.05% p.a., so there is no reason to hold more than that in the account.
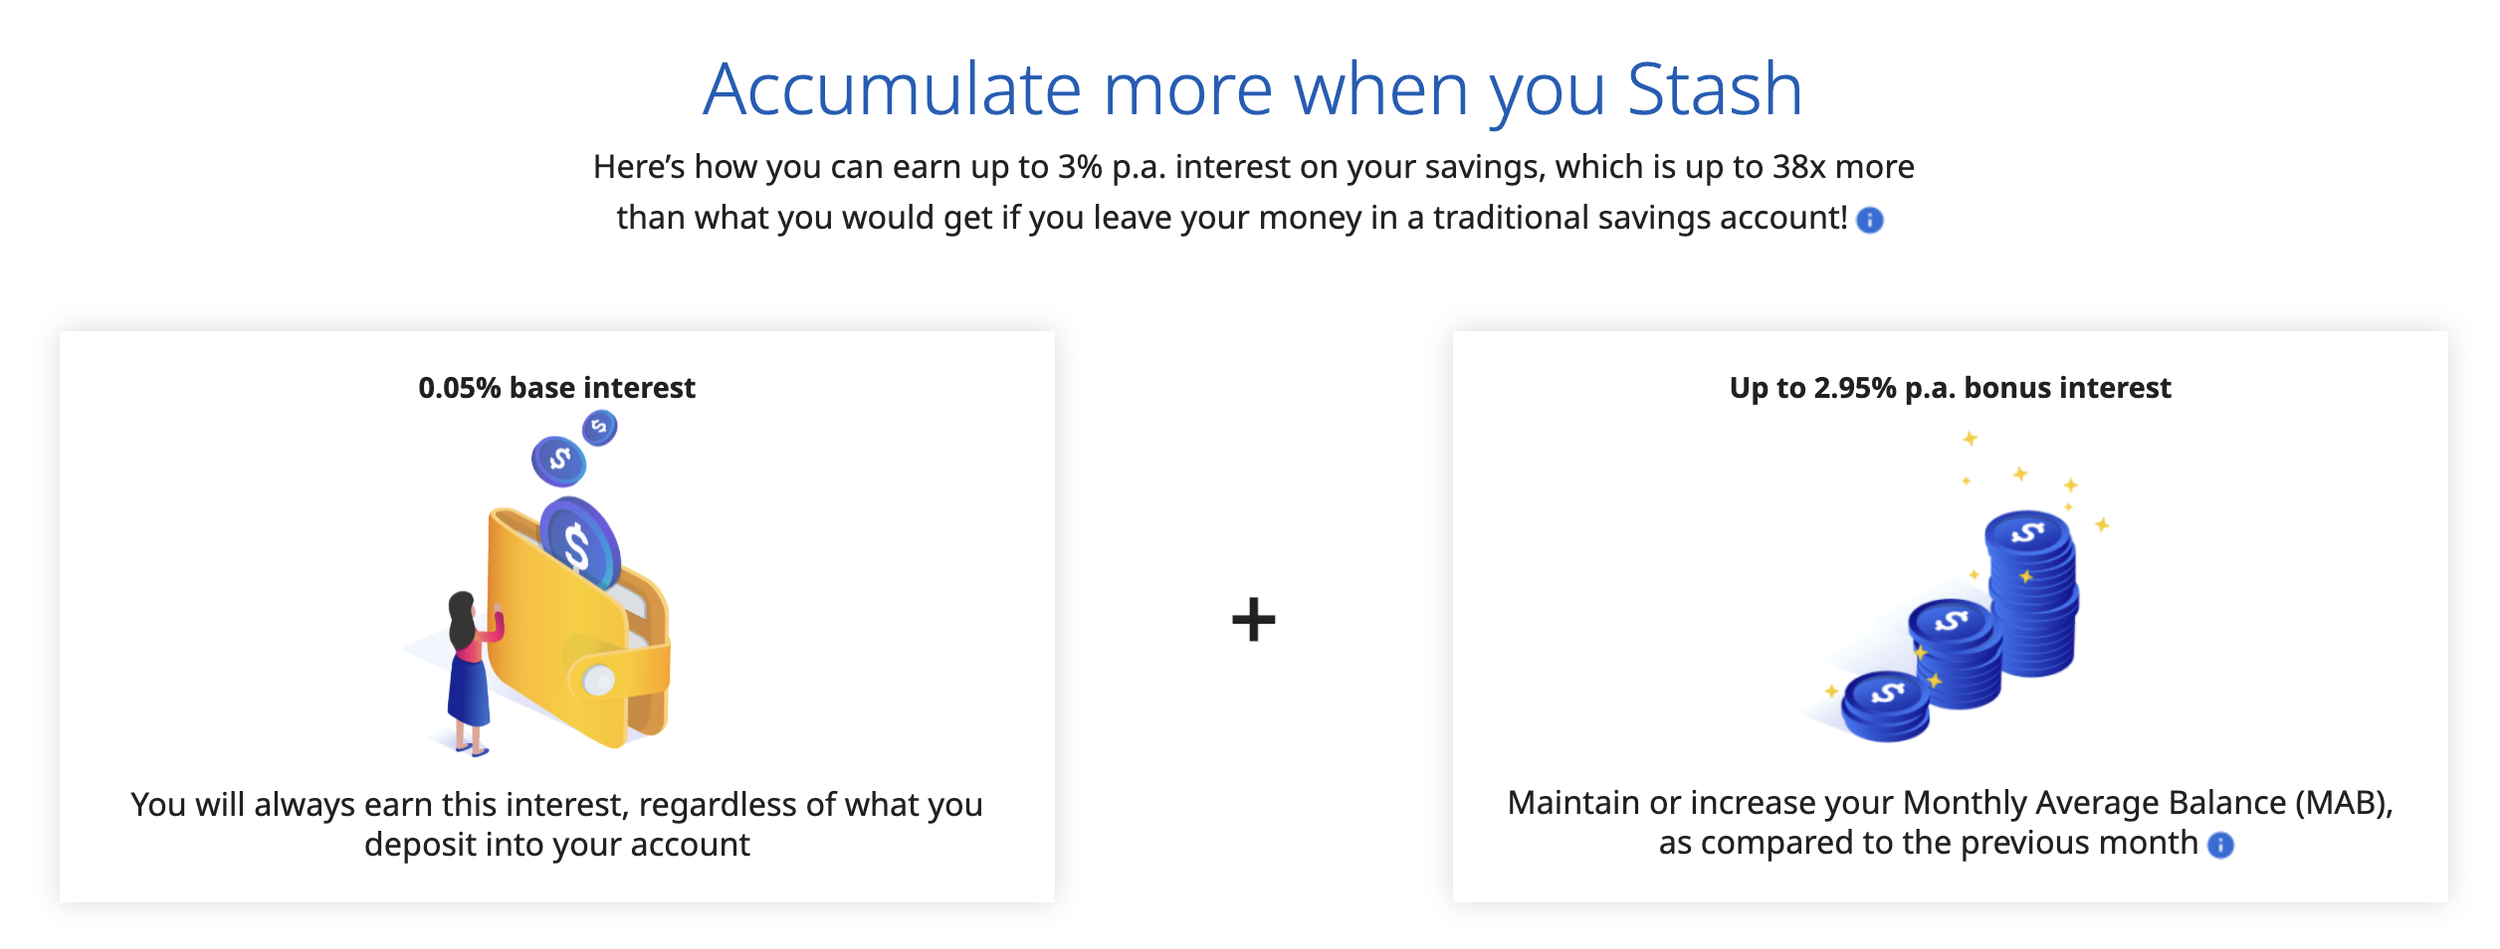
Photo Credit: UOB
What I like about the Stash Account is that it asks very little of you. There is no need to chase minimum card spend or route your salary through UOB, which means your credit card spend can stay on the cards that actually earn you 4 mpd. That separation matters for miles chasers; I would rather not compromise my miles earning just to unlock a savings account bonus.
The elephant in the room is the MAB rule. The Stash Account works best as a set-and-forget emergency fund or a holding account for money you do not intend to touch. If you are the type who regularly moves funds in and out, a single withdrawal resets the clock and you lose that month’s bonus. For anyone who can park S$100,000 and leave it alone, 1.92% p.a. with zero hoops to jump through is a respectable return on cash that is still fully liquid and SDIC-insured. If you only have S$40,000 to set aside, the effective rate is far less compelling, and you may be better served elsewhere.


Seven years after Liang Court closed for redevelopment, Marriott’s first Moxy in Singapore is finally taking shape on the same site, with an opening slated for March 2027.